IMF and UK officials warn of rising debt costs and cyber‑fraud risks as developing nations face financing squeeze
The International Monetary Fund and senior UK officials highlighted growing pressures from higher government borrowing costs and cyber‑attack threats, while Foreign Secretary Ed Miliband called for a new global deal to ease debt burdens on developing countries.
By Lawal Ayo, Editor & Founder · Published 14 Oct 2026, 07:46 WAT
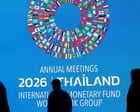
The International Monetary Fund (IMF) has issued a warning about the combined impact of rising government borrowing costs and the increasing threat of cyber‑attacks, according to statements made at the IMF’s recent meeting. IMF Managing Director Kristalina Georgieva highlighted concerns over the speed, scale and cost of fraud, particularly as artificial intelligence tools become more widely used for illicit purposes. She stressed the need for proactive measures to stay ahead of these risks.
Bank of England officials echoed the IMF’s concerns. Governor Andrew Bailey, speaking alongside Georgieva, underscored the heightened vulnerability of financial systems to cyber threats. In addition, the Bank’s chief economist, Huw Pill, cautioned that market expectations of four quarter‑point interest‑rate hikes in the United Kingdom over the next year may be overstated. Pill suggested a more sceptical view of such a tightening path, noting that the appropriate number of hikes remains uncertain.
In a parallel development, UK Foreign Secretary Ed Miliband used the same forum to argue that the global financial architecture is not adequately serving developing economies. He described the current system as failing to meet the needs of countries dealing with heavy debt loads, limited resilience and climate challenges. Miliband called for a "new deal" that would involve the World Bank and other multilateral institutions providing stronger support to governments trapped by high borrowing costs.
Miliband referenced the 2005 Gleneagles summit, which had emerged from the Make Poverty History campaign, as a historical example of coordinated international action on poverty and development. He suggested that a refreshed commitment could also attract greater private investment into emerging markets, thereby improving overall economic stability.
The convergence of these messages points to a broader consensus among international financial leaders: that fiscal pressures, cyber security threats and the structural shortcomings of the existing financial order are interlinked challenges. While the IMF and the Bank of England focused on the immediate risks of debt servicing and digital fraud, Miliband’s appeal highlighted the longer‑term need for systemic reform to support vulnerable economies.
No specific policy proposals were detailed beyond the call for enhanced multilateral assistance and a more cautious approach to interest‑rate policy in the UK. The discussions reflected a shared urgency to address both short‑term financial stability concerns and the deeper, structural issues affecting developing nations.
The statements were made during the IMF’s meeting in Bangkok, where officials from various institutions gathered to assess the global economic outlook and coordinate responses to emerging risks.
Sources
Spotted an error? Report a correction · Corrections policy
More in Business

Judge blocks Trump’s White House ban on CNN, MS NOW and Politico
A federal judge has indefinitely blocked President Trump from revoking press credentials for CNN, MS NOW and Politico, citing violations of First and Fifth Amendment rights and lack of due process.
Lawal Ayo · 14 Oct 2026, 08:54 WAT · 8 sources
French supermarkets suffer massive food loss after cyber‑attack disables refrigeration
A coordinated cyber‑attack forced refrigeration units in hundreds of French supermarkets to heat up, spoiling fresh and frozen goods worth millions of euros and prompting emergency disconnections across several retail chains.
Lawal Ayo · 14 Oct 2026, 04:40 WAT · 2 sources
IMF lifts UK 2026 growth outlook to 1.3% as it warns of global economic strain
The International Monetary Fund raised its forecast for UK GDP growth in 2026 to 1.3% and urged the Labour government to maintain its fiscal consolidation, while warning that low oil inventories and stretched public finances could test worldwide resilience.
Lawal Ayo · 14 Oct 2026, 04:27 WAT · 2 sources